
Why Does Your Money Disappear Before the Month Ends?
Do you reach the end of the month feeling like your money just vanished? You received your salary, paid some bills, made purchases that seemed small — and suddenly, your balance is at its limit. If this sounds familiar, you’re not alone. The lack of a personal budget is one of the main reasons why people with a reasonable income live in financial tightness.
A personal budget is not about deprivation or obsessively tracking every cent. It’s about clarity: knowing where your money comes from, where it goes, and if that destination aligns with what you truly want in life. It’s the difference between being swept away by the current and rowing with direction.
In this article, you’ll learn, step by step, how to create a functional personal budget — whether you’re an absolute beginner or someone who has tried before and given up. The process is simpler than it seems, and the results appear quickly.
What is a Personal Budget (and What It Isn’t)
A personal budget is a financial plan for a specific period — usually a month — that organizes your income and expenses consciously. It answers three fundamental questions:
- How much comes in?
- How much goes out?
- What is left (or missing)?
What it isn’t: a punitive spreadsheet that turns every expense into guilt. Nor is it a promise of quick wealth. A well-made budget helps build financial stability over time but requires consistency and honesty with yourself.
Step-by-Step Guide to Creating Your Personal Budget
1. Map All Your Income Sources
The first step is to know exactly how much money is coming in. List all sources:
- Net salary (after deductions like social security, income tax, health plan, etc.)
- Extra income: freelancing, rentals, odd jobs, occasional sales
- Alimony received, government benefits
- Investment earnings that you already use in your monthly budget
Note: always use net values, meaning what actually goes into your account. Working with gross salary will distort the entire plan.
If your income is variable — as is common with freelancers and entrepreneurs — use a conservative average from the last three to six months. In good months, the surplus goes to a reserve; in bad months, you’re not caught off guard.
2. Record All Expenses (Without Hiding Anything)
This step is where most people stumble: financial self-deception. Expenses on delivery, forgotten subscriptions, impulse purchases — everything needs to be shown.
Divide your expenses into categories:
Fixed expenses — predictable amount every month:
- Rent or mortgage installment
- Condominium fees, property taxes
- School fees, health insurance
- Loan or financing installments
Variable expenses — occur every month, but the amount fluctuates:
- Food (separate groceries and dining out, if possible)
- Transportation (fuel, rideshare, public transport)
- Entertainment, clothing, personal care
- Utilities: electricity, water, internet, mobile phone
Sporadic expenses — don’t appear every month, but happen:
- Annual taxes, car maintenance
- Gifts, trips, occasional medical expenses
For these last ones, estimate the annual expense and divide by 12. Set aside this amount monthly, as if it were a bill. When the expense comes, the money will already be set aside — no surprises.
3. Compare Income and Expenses: Are You in the Black or Red?
With the numbers in hand, do the math:
Total Income – Total Expenses = Balance
If the result is positive, congratulations — you have room to save and invest.
If it’s negative or close to zero, you’ve identified the problem. Now it’s time to act.
Don’t despair over what you find. Many people discover, at this moment, expenses they didn’t even know they had — duplicate subscriptions, unused services, credit card purchases that are “split into 12x” without remembering what was bought.
4. Choose an Organization Method
There is no single method that works for everyone. The most used are:
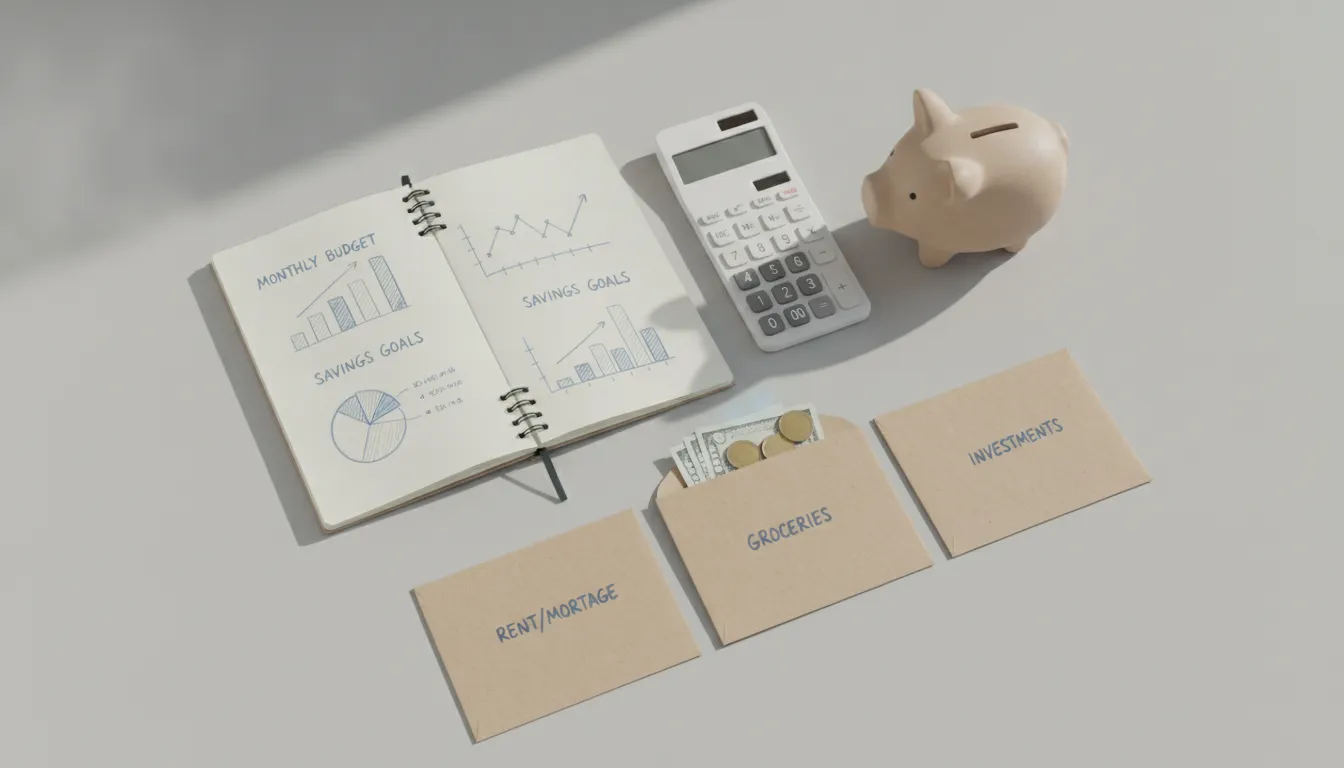
Envelope (or category) method: you set a limit for each category and, upon reaching it, stop spending in that group. It can be done physically (with money in envelopes) or digitally (in apps or spreadsheets).
50-30-20 method: distributes income into three major blocks — needs, wants, and savings/investments. It’s a good reference for beginners. You can learn more about this approach in 50-30-20 Rule: Organize Your Budget with Clarity.
Zero-based budget: every dollar of your income is assigned a purpose until income minus expenses (including savings as “expense”) equals zero. It’s more labor-intensive but gives total control.
The practical recommendation: start with what you can maintain. A simple method executed every week is worth more than a sophisticated system abandoned in the second week.
5. Set Financial Goals and Integrate Them into the Budget
A budget without a goal is just a table. Goals give purpose to daily choices.
Think about goals in three horizons:
Horizon Example Approximate Timeframe Short-term Emergency fund 6 to 12 months Medium-term Down payment on a house, trip, car 1 to 5 years Long-term Retirement, financial independence 5 years or more The emergency fund deserves priority: it is the foundation of any financial plan. The amount recommended by financial educators is usually between three and six months of monthly expenses — more if your income is variable or if you have dependents. This money should be kept in high liquidity (redeemable in one business day) and low-risk investments, such as remunerated accounts or investments tied to the CDI. To know the current CDI value, check the Central Bank of Brazil website (bcb.gov.br).
After setting up the reserve, you can start thinking about where to invest with little money in 2026 according to your goals.
6. Choose Tools to Record and Track
The best tool is the one you will actually use. Some options:
- Spreadsheet in Excel or Google Sheets: flexible, free, fully customizable
- Personal finance apps: there are several options in the Brazilian market; evaluate access permissions and privacy policies before connecting bank accounts
- Notebook or notepad: works for those who prefer analog and have the discipline to note down immediately
- Bank resources: many digital banks offer automatic expense categorizers — useful as a starting point, but check if they cover all your accounts
The secret is not in the tool, but in the frequency of review. Set aside 15 minutes a week to look at the numbers. A more detailed monthly review helps adjust what didn’t work.
7. Review, Adjust, and Repeat
The budget is not a static document. It needs to evolve with you:
- Changed jobs? Review the income.
- Had a child? Fixed expenses increased.
- Paid off a loan? Redirect that amount to another goal.
In the first three months, it’s normal for the budget to be misaligned — you’re still mapping your actual habits. Don’t give up. Over time, the process becomes faster and more natural.
Common Mistakes That Sabotage the Budget
- Forgetting credit card expenses: next month’s bill is this month’s expense. Record at the time of purchase.
- Ignoring annual expenses: annual taxes, insurance, contract renewals. Divide by 12 and provision monthly.
- Creating an unrealistic budget: cutting everything at once rarely works. Gradual reductions have more adherence.
- Not separating personal and business accounts: for freelancers and small business owners, mixing finances is one of the biggest traps.
- Using credit as an income extension: installments and overdrafts are debts, not income. Treating them as such is fundamental.
Conclusion: The Budget is the Starting Point, Not the Destination
Creating a personal budget is the first concrete step to taking control of your finances. It doesn’t solve all problems at once, but it provides visibility — and visibility is the power of choice.
Once you know exactly where every dollar goes, financial decisions become more conscious: to buy or not to buy, to save now or later, to prioritize this goal or that one. Everything starts to make sense within a plan.
Start today, with what you have. A simple spreadsheet, a notebook, or an app. The important thing is to start — and maintain.
This content is for educational and informational purposes only. It does not constitute investment advice, financial product recommendations, or personalized strategies. Each financial situation is unique. For investment decisions or specific financial planning, consult a qualified professional or advisor registered with the Securities and Exchange Commission (CVM).
- Ignoring annual expenses: annual taxes, insurance, contract renewals. Divide by 12 and provision monthly.
- Forgetting credit card expenses: next month’s bill is this month’s expense. Record at the time of purchase.
- Personal finance apps: there are several options in the Brazilian market; evaluate access permissions and privacy policies before connecting bank accounts
- Spreadsheet in Excel or Google Sheets: flexible, free, fully customizable
