
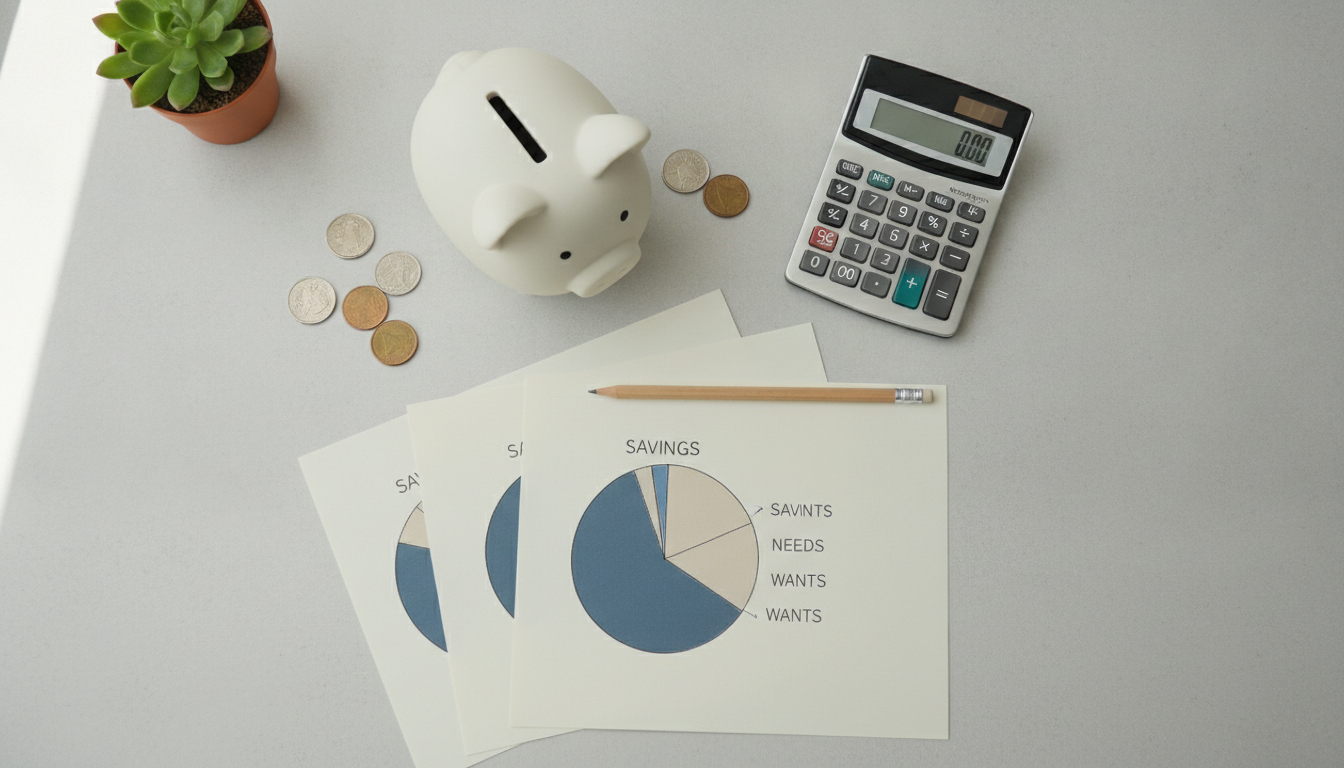
50/30/20 Rule: What It Is and How to Apply It
Have you ever reached the end of the month without understanding where your money went? This feeling is more common than you might think. According to data from the Brazilian Central Bank, household debt in Brazil remains one of the major challenges of domestic finances, with millions of people committing a significant portion of their income just to debt payments. The good news is that there are simple and proven methods to change this scenario — and one of the most popular in the world is the 50/30/20 Rule.
The 50/30/20 Rule is a personal budgeting model created by American senator and law professor Elizabeth Warren, presented in the book All Your Worth: The Ultimate Lifetime Money Plan (2005), written in partnership with her daughter Amelia Warren Tyagi. The proposal is straightforward: divide your monthly net income into three major categories, using fixed percentages as a guide. No complicated spreadsheets or obsessive tracking of every cent — the goal is to offer a light, flexible, and sustainable structure for organizing your finances.
In this article, you’ll understand how the rule works, how to adapt it to Brazilian reality, what its real advantages are, and also its limitations. Because serious financial education is one that presents both sides.
What Is the 50/30/20 Rule
The logic of the rule is simple: every time you receive your net income — that is, the amount that actually reaches your account after deductions for income tax, social security, and other charges — it should be divided as follows:
- 50% for necessities
- 30% for wants
- 20% for savings and investments (or debt repayment)
This division is not a universal law nor does it serve all profiles in the same way. It’s a starting point, a reference. Understanding what fits in each category is the first step to applying the rule with awareness.
The Three Categories Explained
50% — Necessities
These are the essential expenses to keep your life running. This includes:
- Housing (rent, home loan payment, condominium fees, property tax)
- Basic food (grocery store, not restaurants for leisure)
- Transportation (bus, subway, fuel for work)
- Essential utility bills (water, electricity, internet, health insurance)
- Ongoing medications
- Children’s education (when there’s no public alternative)
The keyword here is essential: it’s what would compromise your subsistence or work if you stopped paying.
30% — Wants
These are expenses that improve quality of life but are not strictly necessary:
- Streaming subscriptions
- Restaurants and delivery
- Clothing beyond what’s necessary
- Travel and leisure
- Hobbies
- Beauty and personal care products beyond the basics
Many people make the mistake of calling what is, in practice, a want a “necessity.” The more expensive cell phone plan, the financed car when public transportation works — these are wants disguised as necessities.
20% — Savings, Investments, and Debt Repayment
This portion is what builds your financial future:
- Emergency fund
- Long-term investments (retirement, major goals)
- Early repayment of expensive debt (such as credit card and overdraft)
If you have high-interest debt, prioritize paying off that debt before investing. In Brazil, interest rates on credit card revolving credit are among the highest in the world — consult the Central Bank website (bcb.gov.br) to check the average rates currently being charged. Maintaining expensive debt while investing rarely makes mathematical sense.
How to Apply the 50/30/20 Rule in Practice
Applying the rule requires some initial steps. See a simple step-by-step:
- Calculate your monthly net income. Add all values that actually enter your account: net salary, recurring freelance work, rent received. Don’t use gross income as a base — money that doesn’t reach you can’t be planned.
- Map your expenses from the last month. Use your bank statement, your bank’s app, or a financial control app. Classify each expense in the three categories: necessity, want, or savings/debt.
- Calculate how much is going to each category. Divide the total of each category by your net income and multiply by 100 to get the real percentage.
- Compare with the 50/30/20 model. Where are you spending more than you should? Where is there room for adjustment?
- Make gradual adjustments. If your necessities compromise 65% of your income, you won’t solve this in a month. Identify what can be renegotiated or cut over time.
- Automate what’s possible. Set up automatic transfers to an investment account on payday. This prevents money intended for the future from being consumed in the present.
- Review monthly. The rule is not static. Changes in income, family, or goals demand budget review.
Adapting the Rule to Brazilian Reality
The 50/30/20 Rule was created in the United States, and its direct application to Brazil requires some important considerations.
Income and cost of living in Brazil are very unequal. For those earning up to two minimum wages, keeping necessities at 50% can be a real challenge — housing, food, and transportation can easily consume 70% or more of income in this range. In these cases, the rule serves more as a progressive goal than as immediate reality.
The Brazilian tax system is complex. Workers with signed contracts already have social security and income tax deductions at source. Freelancers and self-employed individuals need to consider these charges when calculating real available net income. Always consult updated tables from the Federal Revenue Service (receita.fazenda.gov.br) to understand your tax bracket.
High interest rates require extra attention. In an environment of high interest rates, as Brazil frequently presents, the 20% category needs to be used strategically. Before any investment, check the current Selic rate on the Central Bank website — it guides the remuneration of many fixed income applications — and compare it with the cost of your debts. The logic is simple: if a debt costs more than any conservative investment yields, paying it off is the best “investment.”
Where to invest the 20%? It is not the purpose of this article to indicate specific products, but it is valid to mention that the Brazilian market offers accessible options for those starting out, such as Direct Treasury (tesouro.gov.br), fixed income applications with FGC protection (Credit Guarantee Fund, for amounts up to R$ 250,000 per institution and tax ID), and investment funds. Every investment carries some level of risk — past returns do not guarantee future results. If you want to better understand where to start with little, see the article Invest 100 reais a month: where to start.
Advantages and Limitations of the Rule
Like every method, the 50/30/20 Rule has strengths and weaknesses. See an honest comparison:
| Aspect | Advantages | Limitations |
|---|---|---|
| Simplicity | Easy to understand and apply, without complex spreadsheets | Can be too simplistic for complex financial situations |
| Flexibility | Adapts to different incomes and lifestyles | Percentages are not always realistic for low incomes |
| Long-term Focus | Ensures space for savings and investments from the start | Does not detail how to invest or where to allocate the 20% |
| Balance | Allows spending on leisure without guilt, within the limit | Can give false sense of control if categories are not well defined |
| Educational | Creates awareness about the proportion of expenses | Does not replace professional financial planning in complex cases |
Common Mistakes When Applying the Rule
- Classifying wants as necessities. The subscriber to four streaming platforms who treats this as an essential expense is distorting the budget base.
- Using gross income as reference. Planning based on a value that is not available generates frustration and imbalance.
- Ignoring variable and annual expenses. Vehicle tax, property tax, insurance, school supplies — these expenses exist and need to be in the planning, even if they’re not monthly.
- Giving up at the first difficulty. No budget works perfectly in the first month. Adjustment is part of the process.
- Not reviewing the rule when life changes. Birth of children, job change, separation — all these events require review of the proportions. Also check the classic mistakes of those starting to invest to avoid common pitfalls on this journey.
Conclusion: Simple, But Not Simplistic
The 50/30/20 Rule is not a magic formula. It won’t solve accumulated debt overnight or guarantee that you’ll get rich. What it offers is something more valuable in the long run: a mental framework for making financial decisions with more awareness and balance.
If you’ve never had a financial organization method, this rule is an excellent starting point. If you already have a method that works for you, use the principles of the rule as a reference to evaluate if your proportions make sense.
The most important thing is to start. Small consistent changes have more impact than big resolutions that last a week. Open your bank statement now, map where your money went last month, and take the first step.
> Important Note: This article is exclusively educational and informative in nature. No information presented here constitutes investment recommendation, financial advice, or personalized consulting. Each financial situation is unique. For investment decisions or financial planning, consult a professional licensed and registered with the Securities Commission (CVM) at cvm.gov.br.
