
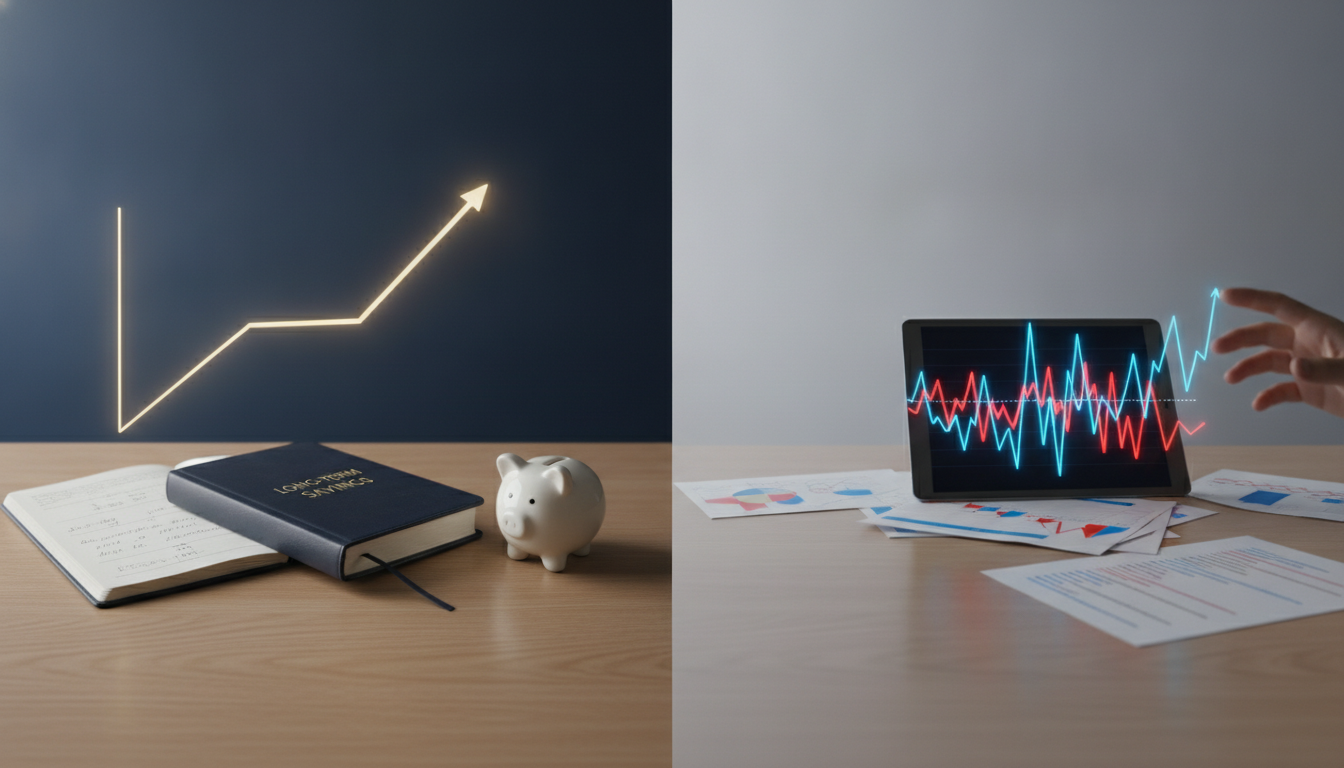
Investing vs. Speculating: What’s the Real Difference?
Have you ever heard someone say they “bought Bitcoin to invest” or that they’re “investing in penny stocks”? These phrases are common in everyday financial vocabulary, but they hide a confusion that can be costly: investing and speculating are not the same thing. The distinction between the two concepts is fundamental for anyone who wants to make more conscious financial decisions aligned with their real objectives.
The problem is that in Brazil, this line is rarely taught in schools or discussed clearly. The result? Many people enter the financial market thinking they’re “investing” when they’re actually speculating — without understanding the risks involved. Others, afraid of “speculating,” end up avoiding the market altogether and missing legitimate opportunities to build wealth over time.
In this article, we’ll explore the real difference between investing and speculating, without unnecessary jargon and without romanticizing either path. The goal is simple: to help you understand which field you’re stepping into — and whether you’re doing so consciously.
What Defines an Investment?
In the most precise sense of the word, investing means allocating resources with the expectation of returns over time, based on solid fundamentals and careful analysis of the asset. The investor seeks consistent wealth growth, generally accepts longer timeframes, and makes decisions based on verifiable data about what they’re buying.
Think of someone who buys a Tesouro Direto bond — a program of the federal government operated by the National Treasury in partnership with B3. When acquiring, for example, a Tesouro IPCA+, this person knows exactly how the return works (inflation measured by IPCA plus a fixed rate), knows the maturity date, understands early redemption rules, and is aware of the credit risk involved. To check current rates available at Tesouro Direto, visit the official website at tesourodireto.com.br — the numbers change daily and any figures cited here could be outdated.
Other classic examples of investment:
- Fixed income: CDBs from solid banks, LCIs, LCAs, debentures with credit analysis.
- Regulated investment funds: supervised by CVM (Securities and Exchange Commission).
- Stocks of companies with fundamentalist analysis: purchase based on financial statements, profits, competitive position, and long-term prospects.
- Real Estate Investment Funds (REITs): with portfolio analysis, management, and income distribution.
The investor does not ignore risk — they analyze it and accept it consciously. Every investment carries some level of risk, even the most conservative ones. What changes is the nature and intensity of that risk.
What Defines Speculation?
Speculation, on the other hand, is an operation where expected gains depend mainly on short-term price variations, often without deep analysis of the asset’s fundamentals. The speculator bets that the price of something will go up or down, and tries to profit from that movement before the market “realizes” what they realized.
This is not necessarily wrong or illegal. Speculation exists in every financial market and, in many cases, it’s what ensures liquidity — that is, the ability to buy and sell assets easily. But it’s important to understand: speculation is inherently riskier and requires skills, time, and structure that most people don’t have.
Examples of typically speculative operations:
- Day trading: buying and selling stocks or contracts on the same day, seeking to gain from small price variations.
- Leveraged operations: using borrowed money or derivatives to amplify positions — which also amplifies losses.
- Purchase of cryptocurrencies without analysis: entering an asset just because “it’s going up” or because someone recommended it on social media.
- Penny stocks: stocks of very small or troubled companies, with extremely high volatility and very low predictability.
The line separating the speculator from the investor lies largely in intention, timeframe, and the basis of the decision. Someone who buys a stock because of a viral post is speculating. Someone who buys the same stock after months of analyzing the company’s fundamentals and intends to hold it for years is closer to investing.
The Gray Zone: When the Line Blurs
In practice, it’s not always easy to classify an operation. Gray zones exist.
A multi-market fund, for example, may have strategies that include speculative operations within a regulated structure managed by professionals. This doesn’t automatically make it unsuitable — but it requires that the investor understand what’s inside the fund before applying.
Similarly, a person who buys Bitcoin could be investing or speculating, depending on the size of the position relative to total assets, the intended timeframe, and the level of understanding about the asset. Cryptocurrencies are extremely volatile assets with no FGC (Credit Guarantee Fund) coverage, which places them in a very different risk category than a bank CDB covered by the fund.
The key is not to demonize speculation, but to recognize it for what it is — and enter it only if you have the financial, emotional, and technical conditions to withstand significant losses.
How the Tax Authority Sees Each One
From a tax perspective, the Brazilian Internal Revenue Service treats short-term operations differently from long-term ones — and this distinction has direct impact on your pocket.
In the stock market, for example:
- Common operations (buying and selling on different days): income tax exemption for total sales up to R$20,000 per month; above that, 15% rate.
- Day trading (buying and selling on the same day): 20% rate, with no exemption, and 1% withholding at the source (known as “informant fee”).
These rules may be updated. To check current 2026 rates and rules, always consult the official Internal Revenue Service website at receita.fazenda.gov.br or see our guide on who needs to file income tax in 2026.
Additionally, losses in day trading cannot be offset with gains in common operations, and vice versa. This technical detail catches many people off guard.
Key Differences in Summary
| Criterion | Investment | Speculation |
|---|---|---|
| Typical timeframe | Medium to long term | Short term (days, hours) |
| Basis of decision | Fundamentals, analysis | Price variation, trend |
| Risk level | Variable, but managed | Generally elevated |
| Taxation (stocks) | Exempt up to R$20k/month | 20%, no exemption |
| Requires | Discipline and patience | Time, technique, and capital |
| FGC guarantee | Some products (e.g., CDB) | Does not apply |
Why This Distinction Matters to You
Understanding whether you’re investing or speculating completely changes how you plan your finances. If you have a fragile emergency fund, high-cost debt, or depend on that money in the short term, speculative operations can be devastating — because volatility and short timeframes don’t mix with immediate liquidity needs.
Before any financial market decision, ask yourself:
- Do I need this money within less than two years? If yes, highly volatile instruments are inappropriate.
- Do I understand what I’m buying? If the answer is no, the operation is much closer to speculation.
- Am I deciding based on data or on emotion/social pressure? The “fear of missing out” (FOMO) is one of the greatest destroyers of wealth.
- Do I have an emergency fund before any risky application? This step is non-negotiable. If you need help organizing your finances before investing, see our guide on how to make a personal budget step by step.
Conclusion: Awareness Before Capital
Investing and speculating are distinct activities that coexist in the financial market. Neither is universally right or wrong — what matters is that you know which one you’re practicing, why, and with how much of your assets.
The big mistake is not speculating. The big mistake is speculating thinking you’re investing, without understanding the risks, without adequate structure, and with money you can’t afford to lose.
Financial education exists precisely to fill this gap. Before putting any resources into any product, take time to understand what you’re buying, how taxation works, what the real risks are, and what CVM and Central Bank regulations say. Information doesn’t eliminate risk — but it significantly reduces the chance of being caught off guard.
> Educational note: This article is for educational and informational purposes only. No content presented here constitutes investment recommendation, financial advice, or indication of specific products or assets. Each person has a unique financial situation, risk profile, and objectives. For personalized investment decisions, consult a qualified professional properly registered with the Securities and Exchange Commission (CVM).
